Zinc aluminium flake coating market projected to reach USD 2.11 billion by 2034
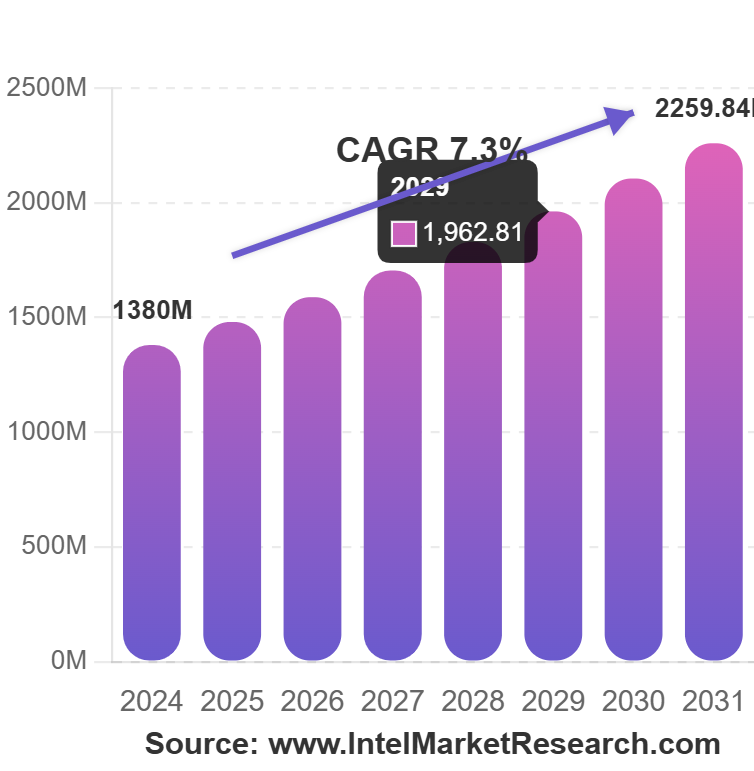
Tighter VOC limits, the phase-out of chromate inhibitors and a build-out of renewable energy infrastructure are reshaping how industry protects steel. Here is what the latest market study says — and what it signals for anyone specifying corrosion protection.
- $1.38B
- Global market value, 2024
- $2.11B
- Forecast value by 2034
- ~4.3%
- Implied annual growth rate
What is pulling demand up
Zinc aluminium flake coatings protect steel two ways at once: the zinc corrodes sacrificially to shield the substrate, while the aluminium flakes form a physical barrier. That combination outperforms conventional galvanising on components that live in aggressive environments, which is why the study points to three demand engines in particular.
Regulation is doing the selling. Tightening VOC limits are pushing specifiers from solvent-based systems toward water-based formulations, and chromate-based inhibitors are being phased out under REACH and equivalent directives. Chrome-free flake systems land squarely in that gap.
Renewables need decades of protection. Wind turbine towers and solar mounting structures sit outdoors for 25 years or more. With the renewable sector growing at a projected 8.4% annually through 2030, it is becoming a meaningful new volume channel for high-durability coatings.
Thinner films, same protection. Formulators are pushing performance into the 5–15µm band, cutting material use per part without giving up corrosion resistance. That thickness range is now the dominant segment of the market.
Where the volume sits
Steel structure protection makes construction the single largest consuming sector. Automotive is the most demanding buyer rather than the biggest one: corrosion specifications for vehicle components are strict, EV programmes are adding new coated parts, and lightweighting favours thin protective films over heavier alternatives. Original equipment manufacturers adopt faster than the repair market, because applying the coating inside the production line gives them control over film thickness and consistency.
| Category | Leading segment | Why it leads |
|---|---|---|
| Film thickness | 5–15µm | Best protection-to-cost ratio, broad substrate compatibility |
| End user | OEMs | In-line application, bulk purchasing, tighter quality control |
| Chemistry | Water-based | Meets low-VOC rules; durability now rivals solvent systems |
| Application method | Spray | Thickness control on complex parts, fits automated lines |
The pressure points
Growth is steady rather than explosive, and the study is clear about why. Raw materials account for roughly 60–70% of production cost, so every swing in zinc and aluminium prices lands directly on margin — a hard position to hold in competitive tendering. Application is the second constraint: complex geometries and very large surfaces are expensive to coat well by conventional spray. And graphene-enhanced and nanotechnology-based systems are drawing R&D money that could take share in specific niches, even where flake coatings still hold the performance edge today.
The regional picture
- Asia-Pacific — the largest market and a net exporter. Chinese, Japanese and Korean manufacturing sets the pace, backed by integrated raw material supply and heavy infrastructure spending.
- Europe — sets the formulation benchmarks, particularly German and Italian producers. Automotive underbody protection is a core specified application.
- North America — skews toward aerospace, defence and oil and gas maintenance, with regulation driving chromium-free reformulation.
- Middle East & Africa — pipeline and refinery work in the GCC, plus mining equipment in Africa. Heat and sand erosion drive local formulation changes.
- South America — Brazilian automotive and Argentine agricultural equipment are the growth pockets, held back by economic volatility.
What it means for surface finishing
The direction of travel is the same one running through electroplating: away from chromates, away from high-VOC chemistry, and toward finishes that deliver the same salt spray performance with less material on the part. Plants that can hold tight film thickness consistently — and document it — are the ones that will keep qualifying for OEM work. It is the direction Marshal Laboratories already builds for, with water-based zinc flake coating chemistry and top coats applied on our own DIP–SPIN plants.
Source: third-party market research on the global zinc aluminium flake coating market, forecast period 2024–2034. Figures are as published by the report author.